
Ghana's US$393m Tullow Tax Arbitration: How a 2016 Jubilee Breakdown Led to a Landmark Tax Ruling
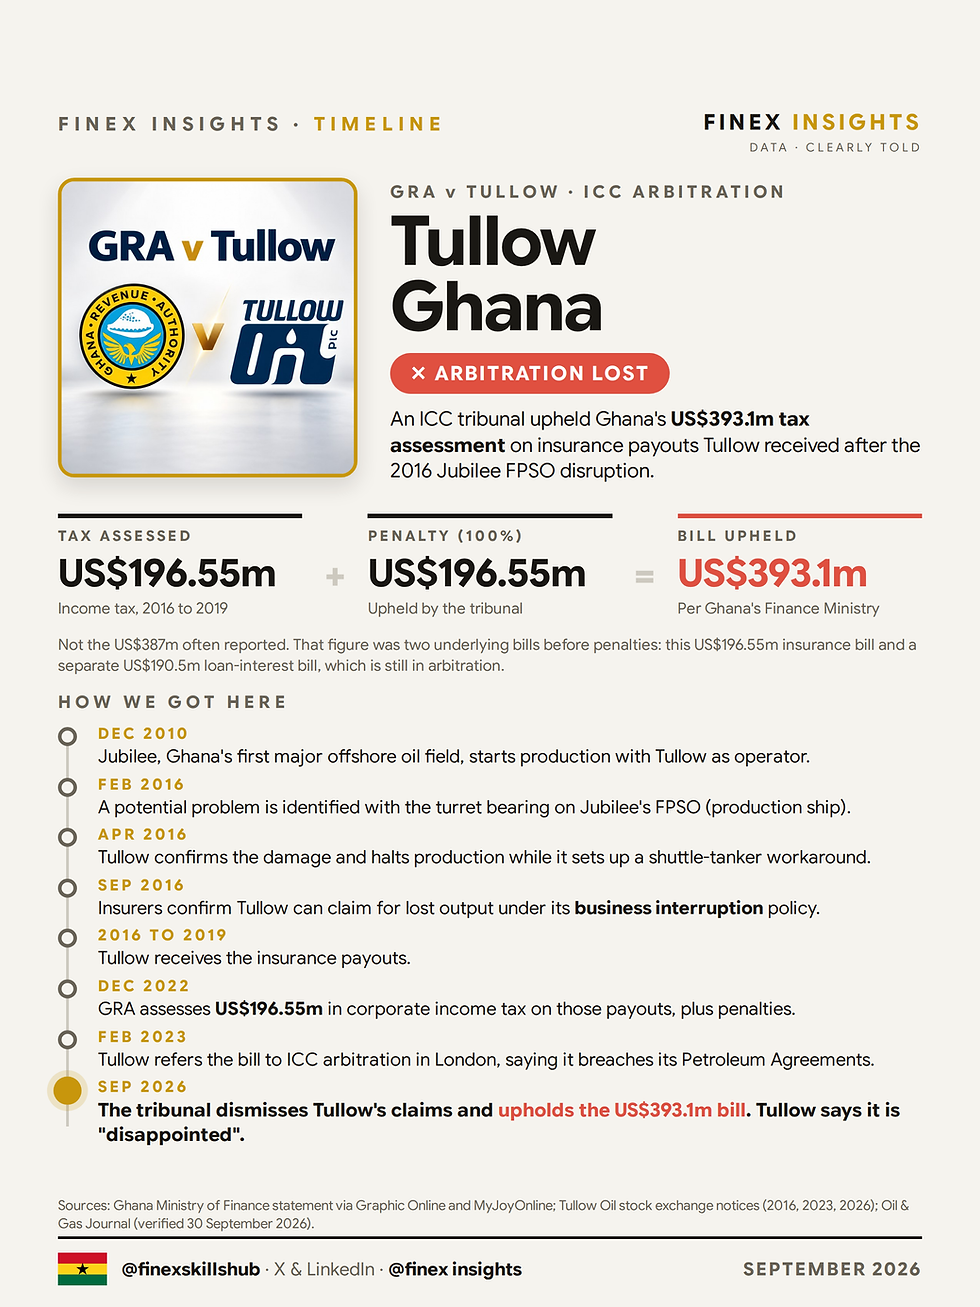
A technical problem aboard Ghana's Jubilee oil field in 2016 eventually developed into a tax dispute worth almost US$400 million. On September 29, 2026, an arbitral tribunal constituted under the Rules of Arbitration of the International Chamber of Commerce ruled in favour of Ghana in a dispute brought by Tullow Ghana Limited. The tribunal dismissed Tullow's claims and upheld the Ghana Revenue Authority's tax assessment of US$393,091,993.70 relating to business interruption insurance proceeds. Graphic
The size of that figure can obscure the more interesting story: how did an operational problem at an oil field turn into a US$393 million tax liability?
It started with Jubilee
The chain of events stretches back to 2016.
A potential problem with the turret bearing of the FPSO Kwame Nkrumah was identified in February. By April, Tullow confirmed that the bearing had been damaged and could no longer rotate as designed. The problem required new operating procedures and contributed to an extended production shutdown. Production subsequently resumed under revised arrangements involving shuttle and storage tankers. Tullow Oil
The financial consequences were significant enough to trigger Tullow's insurance coverage.
In September 2016, Tullow announced that its lead insurers had accepted a recoverable claim under the company's Business Interruption insurance policy. The coverage included lost production associated with the bearing failure and downtime required to restore operations. Tullow Oil
Tullow's 2016 accounts show that it recorded US$145 million in insurance proceeds that year, including US$90.1 million related specifically to lost production. Further proceeds were received subsequently. Tullow Oil
The insurance money became a tax dispute
Years later, the Ghana Revenue Authority took the position that proceeds Tullow received under its Business Interruption insurance policy were subject to corporate income tax.
In December 2022, Tullow Ghana received a US$196.5 million corporate income tax assessment, together with an associated penalty of approximately US$196.6 million. The assessment related to insurance proceeds received during the 2016 to 2019 financial years. Ghana Stock Exchange
That brought the disputed liability to approximately US$393.1 million.
Tullow disagreed with the assessment. The company argued that it breached its rights under its Petroleum Agreements and, in February 2023, referred the dispute to ICC arbitration. Investegate
Ghana prevailed
The tribunal ultimately rejected Tullow's challenge.
According to Ghana's Ministry of Finance, the tribunal found that the tax assessment did not breach the Petroleum Agreements. It also determined that the penalty had been properly applied, that the assessment was not time-barred and that the GRA's enforcement action was lawful. Graphic
The result leaves the US$393,091,993.70 assessment intact.
But that does not necessarily mean US$393.1 million immediately enters government coffers. The Ministry of Finance says implementation will take into account the continuity of Tullow's operations and its capacity to continue investing in the Jubilee and TEN fields. Ghanaian law also gives the GRA authority over the timing and manner in which assessed liabilities are paid. Graphic
That distinction is important when interpreting the ruling's immediate fiscal impact.
Why some reports previously mentioned US$387 million
There is another source of potential confusion.
Tullow was simultaneously contesting a separate US$190.5 million tax assessment relating to the disallowance of loan-interest deductions for the financial years 2010 to 2020. FinancialFilings
Adding that US$190.5 million assessment to the original US$196.5 million insurance-related tax assessment gives US$387 million, explaining the figure that appeared in earlier disclosures concerning the two underlying assessments.
The US$393.1 million figure upheld in the latest ruling is different. It relates to the insurance case alone once the associated penalty is included.
That makes the distinction critical: Ghana's latest arbitration victory resolves the challenge to the insurance-related assessment, while the loan-interest matter is a separate dispute.
A dispute ten years in the making
The most striking feature of the case may be its timeline.
What began as a mechanical problem on the Jubilee FPSO in 2016 triggered an insurance claim. Those insurance proceeds subsequently generated a corporate tax assessment. That assessment led to international arbitration and, almost a decade after the original operational disruption, a US$393.1 million ruling.
It is a reminder that in the petroleum industry, the financial consequences of an operational event can continue long after production has resumed. Join our WhatsApp group to receive data viz insights on Ghana and Africa directly: https://chat.whatsapp.com/JCqBvBWfqjILTxiaCqFhCx?mode=wwt


Comments